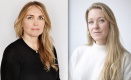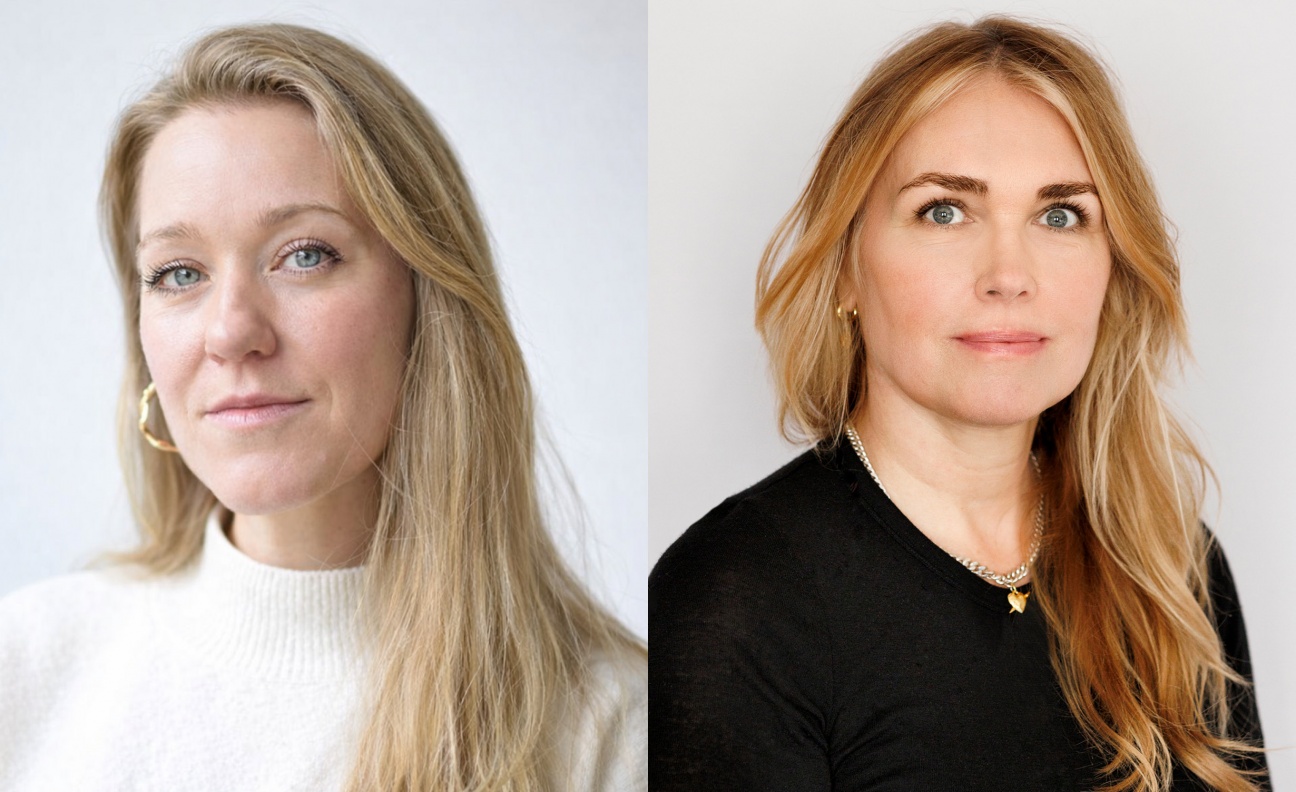
Founded by Linda Collin and Åsa Enström, Rights Intelligence is a new consultancy offering specialist guidance on music licensing and rights management.
The pair aim to build licensing structures that are fair, transparent and sustainable. Here, amid the rise of pan-European agreements, they question the “mega-hub” licensing model…
For decades, copyright administration was relatively straightforward. Every country had its own performing rights organisation, which licensed and administered its domestic music repertoire. On the publishing side, they were essentially national monopolies.
Then digital services arrived, and with them a licensing problem Europe had never faced before. The old system of reciprocal agreements, where royalties flowed through convoluted, territory-by-territory chains, became slow and inefficient.
The EU’s answer was pan-European digital licensing, formalised in the 2014 Collective Rights Management (CRM) Directive. This legal framework was designed to reduce administrative complexity, enable rights-holders to receive royalties directly, and make it easier for DSPs to obtain licences covering multiple countries. To achieve this, societies were encouraged to pool their resources and invest in better technology. On paper, this was a win-win – more bargaining power for smaller societies, and less negotiation friction for DSPs.
However, the directive introduced strict technical rules. Article 24 demanded massive data processing capacity to handle these multi-territorial licences. If you could not meet the bar alone, you had to join someone that could.
Then the market exploded. Negotiations suddenly involved user-generated content, livestreaming, long/short-form video and peer-to-peer monetisation. Contracts grew from a handful of pages into documents spanning fifty pages or more, with updates arriving almost as quickly as the time it took to conclude a negotiation.
Keeping pace meant building specialist legal and data teams, which simply wasn't realistic for smaller societies. So societies began doing exactly what the legislation had hoped they would do. They formed licensing hubs.
Yet there is a crucial distinction to be made here: Article 24 requires capacity, not size. Data processing, claiming and reporting can all be outsourced to third-party tech providers. The one thing a hub offered that couldn’t be bought was negotiating power. By pooling resources, the largest societies could license their repertoire across Europe, bypassing hundreds of reciprocal agreements. Fewer intermediaries meant far greater control over the value of their catalogues, fewer administrative deductions, and more consistent reporting.
Today, less than a handful of these mega-hubs negotiate on behalf of the overwhelming majority of European repertoire. What started as an attempt to reduce the administrative burden has consolidated licensing into an oligopoly, concentrating data, negotiation power, and standard-setting into very few hands. The upfront rewards are obvious: smaller societies avoid years of legal negotiations, secure better initial rates, and save money by using a hub partner for invoicing.
But what happens when you ask, “Why does my statement look like this”, or “Hey, our member had a viral hit on TikTok, but the royalty statement isn’t reflecting this?” What happens when you ask for residual and reciprocal statements or try to understand how flat fees are distributed?
Scale remains useful, but bespoke knowledge is becoming the more valuable negotiating asset
Linda Collin and Åsa Enström
This is where the hub structure shows its limitations. A simple data request often passes through several internal departments before reaching a third-party reporting provider, which must then isolate your specific repertoire from the wider dataset. Every additional link in the chain adds complexity, time, and distance between the rights-holder and their own data. Without direct access to underlying data, societies cannot test the methodology to see if they are being paid fairly.
Transparency is not about curiosity; it is about establishing true financial valuation. And it is worth remembering that under the CRM Directive, transparency is a legal entitlement, not a favour to ask for.
The terms of a deal negotiated by a massive hub might be highly advantageous for a society with a huge catalogue built on scale and variation. However, those exact same terms can be genuinely damaging for a smaller repertoire built on cultural or niche music. When a hub accepts a principle or reporting compromise with a DSP, it effectively becomes the standard for everyone under that umbrella. Smaller societies end up inheriting these terms without ever being in the negotiation room.
Now, the game has changed again. The EU's 2021 Digital Single Market Directive, specifically Article 17, altered the logic of this entire structure. This law makes platforms that host user-uploaded content directly liable for copyright. In short, DSPs must now negotiate with rightsholders regardless of size, and provide the data to support that negotiation.
And this is where the justification for the hubs starts to wobble. The responsibility and the risk for licensing now sit with the platforms. The authorisation sits with the individual rights-holder. Scale is no longer the necessity it once was.
So if platforms carry the risk, why are rights-holders still locked into concentrated hubs? Have we simply replaced territorial fragmentation with something else: an oligopoly that sets standards for everyone?
The next generation of negotiations will not be won by whoever represents the largest catalogue. Rather, it will be won by whoever best understands their underlying data, user behaviour, commercial value, and the legal framework. This means having the agility to negotiate on your own terms, defining success based on what actually works for your specific repertoire rather than accepting a blanket market standard. Scale remains useful, but bespoke knowledge is becoming the more valuable negotiating asset.
Having sat on every side of this table – inside a hub, negotiating across from one, and auditing on behalf of those within – the conclusion from all angles is the same. A hub may still be the right choice for some societies, but it should be a choice made with full sight of the shortcomings, not a default inherited from a reading of the law that no longer holds.
The question every society inside a hub should be asking is simple: if you could see the full picture, would you still choose this one?